The Complete Veteran Home Buyer's Guide
Understand the VA home loan benefit before you start shopping for a home.
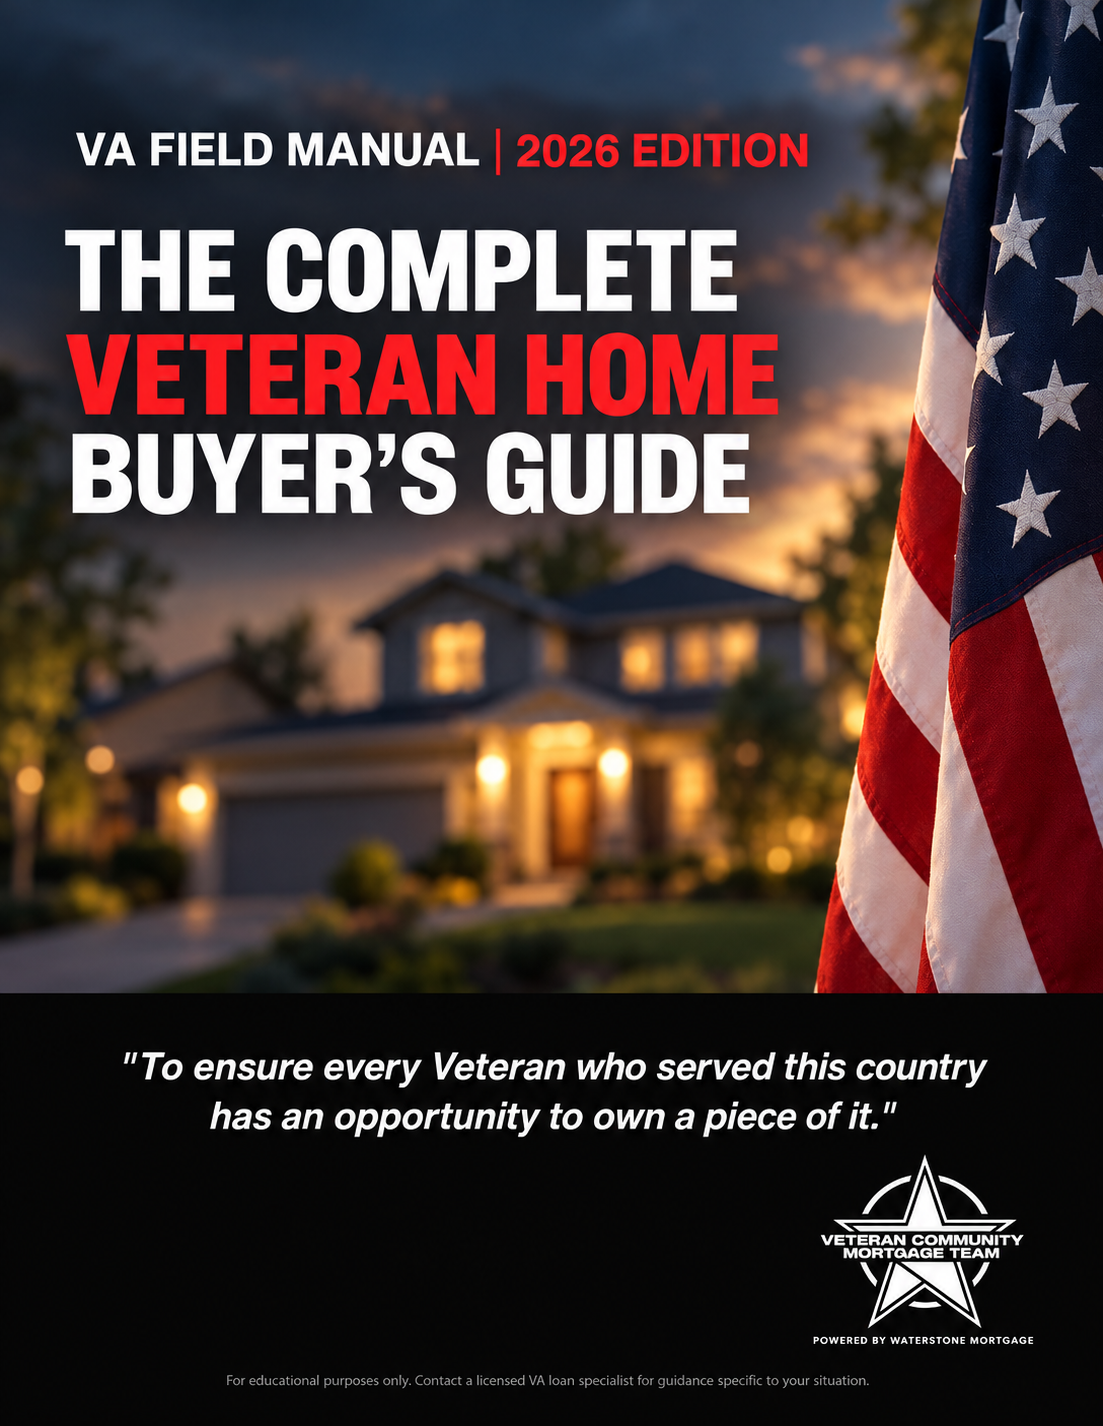
The VA home loan is one of the most valuable benefits earned through military service, but understanding eligibility, entitlement, costs, appraisals and the purchase process can feel complicated. This free guide puts the major pieces in one place so you can make better-informed decisions before and during your home search.
Know the Benefit Before You Need It
The VA home loan benefit can be used for more than a first home purchase. Depending on eligibility and entitlement, Veterans and service members may be able to use the benefit again, hold more than one VA-backed loan, refinance an existing VA loan, assume or transfer certain VA loans, or explore eligible construction financing. The goal of this guide is to help you understand the questions to ask before the transaction gets complicated.
The Figures Every VA Buyer Should Know
Inside the Guide, You'll Learn
Overview: the VA home loan guarantee
Created by the original G.I. Bill in 1944. How the VA guarantee replaces the down payment, plus the eight reasons to choose a VA loan: no down payment, no PMI, no loan limit with full entitlement, competitive rates, seller-paid closing costs up to 4%, no prepayment penalty, a reusable benefit and the VA IRRRL.
Eligibility: who qualifies
The service-category table showing minimum requirements for active duty, Gulf War, Vietnam, post-Vietnam and peacetime eras, Reserves and Guard (6-year and active-duty paths), service-connected disability discharges and eligible surviving spouses, plus why discharge status matters.
Certificate of Eligibility (COE)
Three ways to get your COE (through your lender in seconds, online at VA.gov, or by mail with VA Form 26-1880), the proof-of-service documents you'll need (DD-214, statement of service, NGB-22/23), and what to do if your COE is denied.
Before you buy: getting started
The six-step prep sequence: get your COE, review your finances (no VA minimum credit score, most lenders look for 580 to 620+), shop multiple lenders within a 45-day window, choose a VA-experienced agent, get pre-approved and shop for a home that meets Minimum Property Requirements.
Costs: what you'll actually pay
The one-time closing cost table (funding fee, appraisal at roughly $500 to $900, closing costs with origination capped at 1%, optional down payment, inspection, points, title insurance) and the recurring monthly costs to budget for.
VA funding fee tables
The 2026 purchase and construction fee table (2.30% first use and 3.60% subsequent use at $0 down, 1.65% at 5%+ down, 1.40% at 10%+), fees for cash-out, IRRRL, assumptions and manufactured homes, who is exempt, and the 2029 change to 1.40%.
The VA purchase process: step by step
What you can and cannot buy with a VA loan, the Minimum Property Requirements, and the 30-day loan timeline from pre-approval (days 1 to 3) through offer, appraisal, underwriting, clear to close and closing day.
Appraisal, Escape Clause and home inspection
How the VA appraisal works, your four options if the appraisal comes in low (ROV, renegotiate, bring cash or walk away), the required VA Escape Clause language, and how to pick a home inspector.
Additional VA loan options
Reusing your benefit and restoring full entitlement, buying a second home with remaining entitlement ($832,750 conforming limit in 2026), the $6,000 Energy Efficient Mortgage, VA construction loans and loan assumptions at a 0.50% fee.
Documents, closing and post-purchase
The document checklist your lender will need (COE, DD-214, W-2s, LES or pay stubs, bank statements, tax returns and more), what happens at closing with the 3-business-day Closing Disclosure, and how mortgage servicing works after you close.
Frequently asked questions
Ten straight answers: minimum credit score, buying overseas, co-borrowers, holding more than one VA loan, active duty for training, bankruptcy waiting periods, what happens to the loan if you die, first-time-buyer myths, Guard and Reserve training, and repair loans.
Ready to use the benefit you earned?
How to schedule a free 15-minute call with Jason Stier, Director of VA Lending, and the Veteran Community Mortgage team, with no jargon and no runaround from first call to keys in hand.
Start With These VA Home Loan Basics
Yes. The VA home loan benefit is reusable. How you use it again depends on the entitlement currently available and what happened with any prior VA-backed loan.
Read the full answerThe Department of Veterans Affairs does not establish one universal minimum credit score for all VA-backed loans. Lenders evaluate credit and may establish their own requirements.
No. The VA appraisal addresses value and applicable property requirements. An independent home inspection evaluates the home's systems and condition in greater depth.
Read the full answerIt can be possible when sufficient entitlement remains and the borrower meets applicable occupancy and qualification requirements.
Read the full answerVA-backed financing can support eligible construction transactions, but construction lending is specialized and the financing structure should be reviewed before committing to a builder or property.
Read the full answerGet the Complete 2026 VA Home Buyer Guide
Want the complete field manual? Tell us where to send it and we'll email you the PDF.
Created for Veterans and Military Families
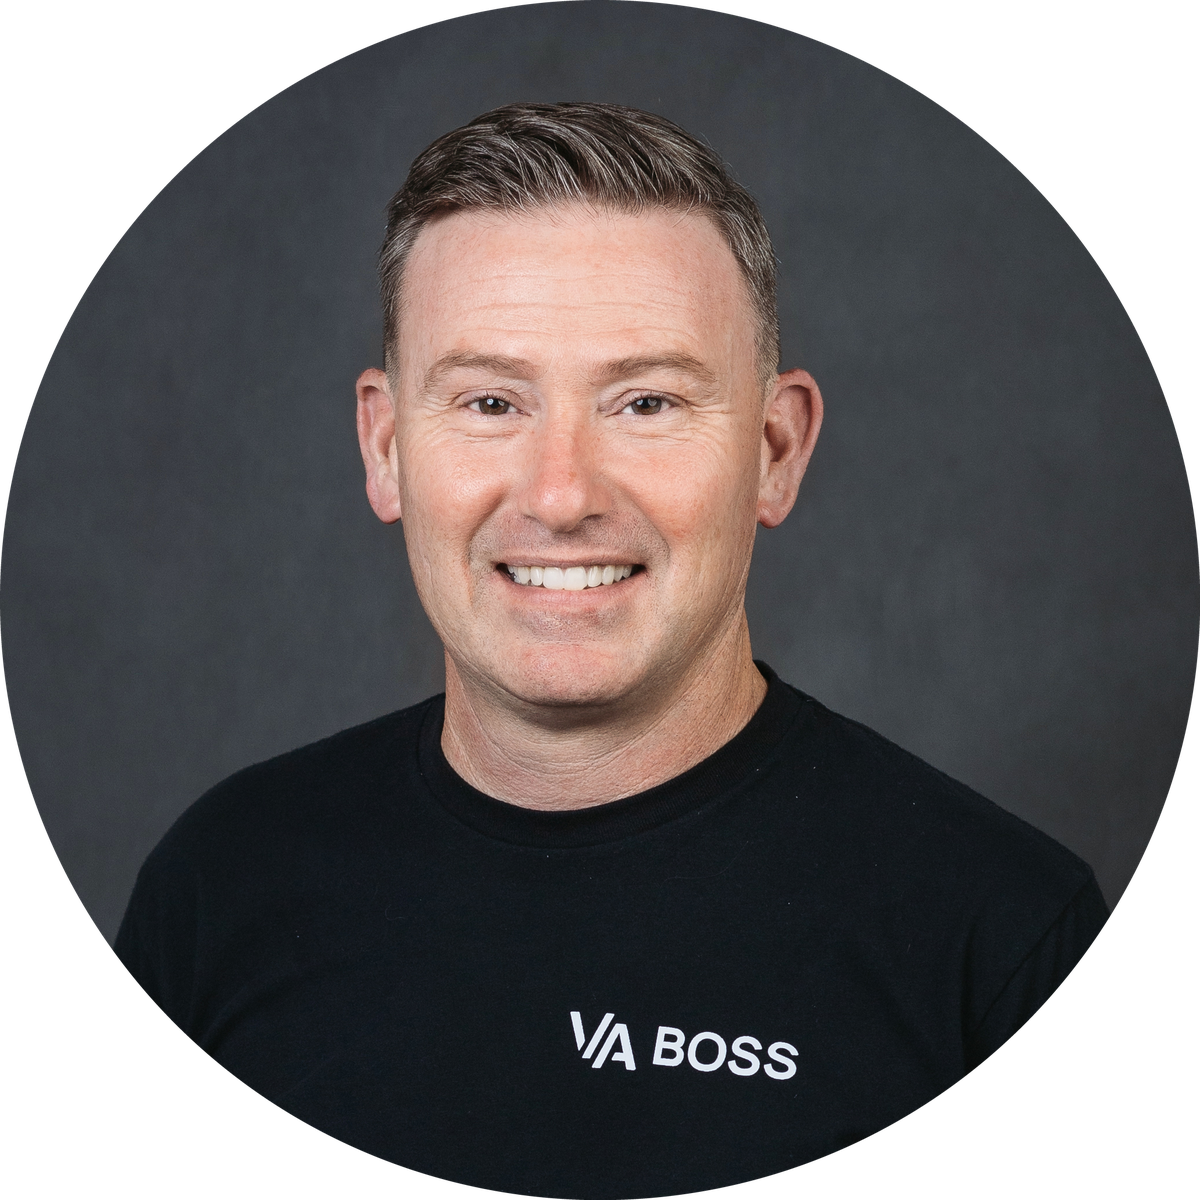
Jason Stier is the VA Loan Boss, founder of Veteran Community Mortgage and a VA loan educator with more than two decades of mortgage-industry experience. His work focuses on helping Veterans, active-duty service members and military families understand the benefit they earned and build a home financing strategy around their actual situation.
Meet Jason StierWhat Happens After You Request the Guide?
Check your inbox
The complete VA Home Buyer Guide is delivered by email.
Use it as your field manual
Review the sections that apply to where you are in the homebuying process.
Ask a question when you have one
If something in the guide raises a question about your eligibility, entitlement, property or next move, reply to the email or start a VA loan strategy conversation.
Straight Answers From the Knowledge Center
Ready to Talk Through Your VA Homebuying Strategy?
The guide gives you the framework. Your actual eligibility, entitlement, finances, property and plans determine the strategy. When you're ready, talk through your situation with Veteran Community Mortgage.