Can Military Retirement or VA Disability Income Be Used to Qualify for a Mortgage?
Yes. Documented military retirement income and eligible VA disability compensation can generally be considered when qualifying for a mortgage when the income meets applicable VA and lender requirements. The documentation and analysis can differ depending on whether the borrower is already retired, approaching retirement or receiving disability compensation.
Military Retirement
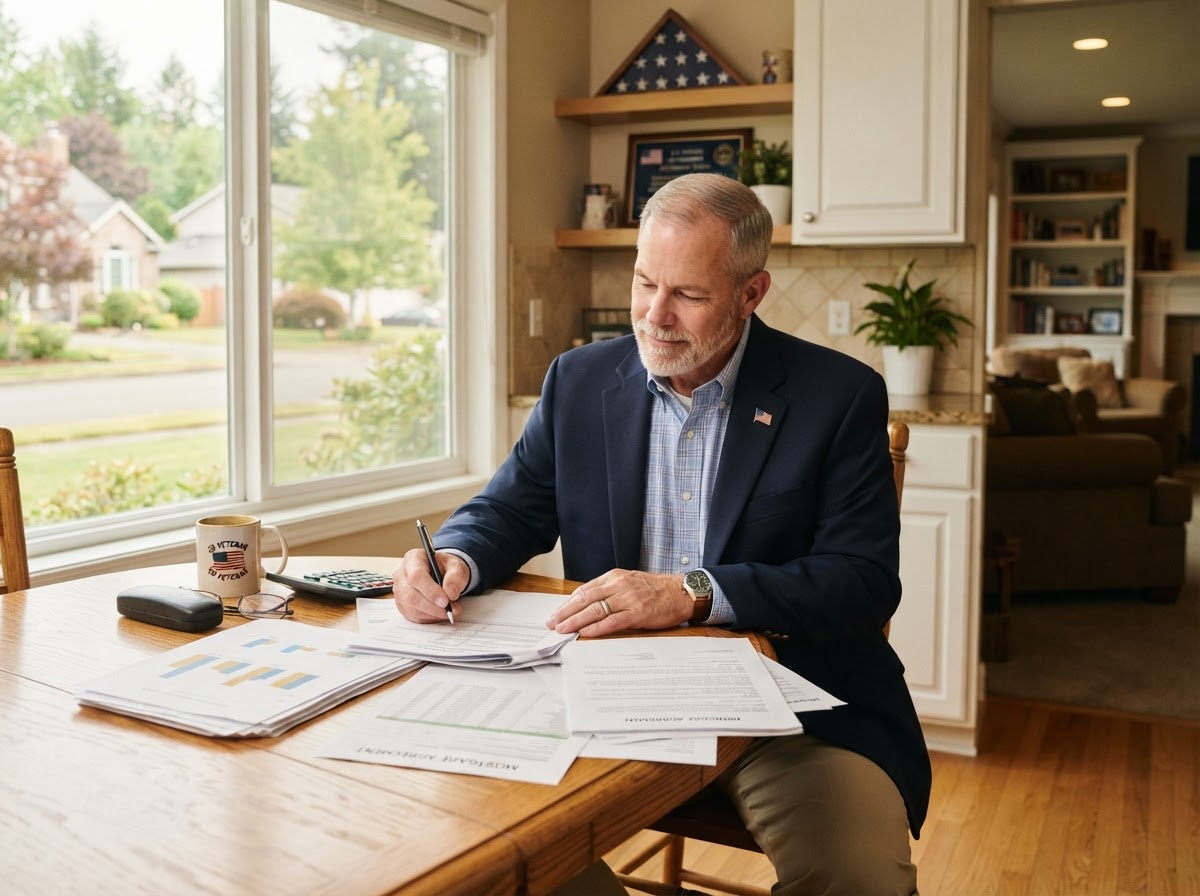
For a borrower already receiving military retirement income, the lender generally
documents the income and evaluates it under applicable requirements.
When retirement is approaching but has not yet occurred, timing matters. The lender
needs to understand the retirement date, expected income, employment plans if
applicable and whether the income used to qualify can be documented and expected to
continue as required.
VA Disability Compensation
Eligible VA disability compensation can generally be considered qualifying income when
properly documented.
Because qualifying rules can treat certain non-taxable income differently from taxable
income, the lender should evaluate the actual documented income rather than assuming
it is treated exactly like wages.
Jason's Take
Military retirement is a transition, not just an income line on an application. If you plan to buy near retirement, start the mortgage conversation early enough to map the retirement date, future income and move together instead of waiting until you are under contract.
Reviewed by Jason Stier
Jason Stier is the VA Loan Boss, founder of Veteran Community Mortgage and a VA loan educator with more than two decades of mortgage-industry experience. His work focuses on helping Veterans, military families and housing professionals better understand the VA home loan benefit.
Have a VA Loan Question? Start With the Strategy.
Every VA loan scenario is different. The next step is understanding how the benefit, your finances and your plans fit together.