V
VA Home Loans for Veterans & Military Families
VA Home Loan Experts for Veterans & Military Families
Using your VA home loan benefit should not be confusing.
Veteran Community Mortgage helps Veterans, active-duty service
members and military families understand their VA home loan options,
build the right strategy and move forward with confidence from first-time
homebuying and PCS moves to refinancing, military retirement and VA construction.
⚑ VA Home Loan Education
♙20+ Years of Mortgage Experience
♡ Veteran & Military Family Focused
☆ Led by VA Loan Educator Jason Stier
VA Topics
Your VA Benefit Is More Than a Loan Program. Know How to Use It.
The VA home loan is one of the most valuable benefits earned through military service,
but the rules can feel complicated. Our job is to make them easier to understand and
help you build a strategy around your actual situation.
VA Loan Eligibility & Entitlement
Understand who is eligible, how entitlement works, whether you can use the benefit more than once and what happens when you already have a VA loan.
Buying With a VA Loan
Buying With a VA Loan
Learn how VA financing works from pre-approval through closing, including offers, closing costs, seller concessions and the VA appraisal.
PCS & Military Moves
Buying before a PCS? Deciding whether to sell or rent? Moving before the family arrives? Start with guidance built around the realities of military relocation.
Military Retirement &
VA Disability
Understand how military retirement, pending retirement and eligible VA disability income may affect your homebuying strategy and mortgage qualification.
VA Refinancing &
Assumptions
Learn how VA IRRRLs, VA cash-out refinancing and VA loan assumptions work and when each option may or may not make sense.
VA Construction Loans
Want to build instead of buy an existing home? Learn how VA construction and One-Time Close financing can work for eligible Veterans and service members.
Meet The VA Loan Boss
With over 21 years of experience in the mortgage industry, Jason Stier has built a reputation as a trusted, knowledgeable, and approachable loan officer who goes above and beyond for his clients. Known as the “VA Loan Boss,” Jason combines expertise with a deep passion for serving Veterans, military members, and their families through Veteran Community Mortgage. His mission? To ensure those who’ve served our country can navigate the path to homeownership with confidence and ease.
Jason’s years in the industry have sharpened his greatest skills: expert communication, problem-solving, and the ability to simplify complex financial processes. Whether breaking down the nuances of VA loan benefits or navigating challenging credit situations, Jason excels at turning what can feel overwhelming into an empowering experience.
When Jason isn't helping Veterans achieve their homeownership goals, he enjoys spending quality time with my family, traveling, and staying active through golf and pickleball. He's also passionate about connecting with and supporting Veteran-focused charities and organizations that make a positive impact in the lives of those who have served our country. Giving back to the Veteran community is something he values deeply, both professionally and personally.
Start With Your Situation
Where Are You in the Process?
You do not need to know every VA rule before you start. Find the situation that
looks most like yours and begin there.
I Want to Buy a Home
Understand your VA eligibility, buying power,
pre-approval and what to expect from offer to closing.
I Have PCS Orders
Build a housing strategy around your move,
timeline, current home and next duty station.
I Already Own a Home
Explore VA refinancing, assumptions, remaining entitlement and options for using your benefit again.
I Want to Build a Home
Learn how VA construction and One-Time Close
financing can help eligible borrowers finance a new build.
VA Home Loan Knowledge Center
Get Straight Answers
About the VA Home Loan
You should not have to dig through lender sales pages, social media
opinions and outdated information to understand your VA benefit.
The Veteran Community Mortgage Knowledge Center is being built to
answer the questions Veterans and military families actually ask in
plain English, with direct answers, real-world context and links to
authoritative sources when the rules matter.
The VA Process
How the VA Home Loan Process Works
Every situation is different, but most VA home purchases
move through these five stages.
Build Your Strategy
We start with your goals, military timeline, finances and how you plan to use the property.
VA Loan Pre-Approval
We review your qualification and VA eligibility so you understand your buying range before you start making offers.
Find the Right Home
You and your real estate agent search for a property that fits your needs, budget and VA financing strategy.
Appraisal & Underwriting
The property and loan are reviewed, including the VA appraisal and the documentation required for final loan approval.
Closing
Once the loan is cleared and closing requirements are satisfied, you sign the final documents and complete the purchase.
Why VCM
Why Veteran Community Mortgage?
We built Veteran Community Mortgage around a simple belief: military families
deserve more than a lender who happens to offer VA loans. They deserve
people who understand the benefit, teach the process and know the questions
to ask before problems show up.
VA-Focused Guidance
Our education, process and resources are
built around the VA home loan and the situations
military families regularly face.
Education Before Pressure
We want you to understand the benefit,
the numbers and the tradeoffs before you
make a decision.
Strategy for Real Military Life
PCS orders, deployments, retirement, disability income, existing VA loans and future moves can change the strategy. We account for the bigger picture.
I Want to Build a Home
Learn how VA construction and One-Time Close
financing can help eligible borrowers
finance a new build.
Don't take my word for it
Frequently Asked Questions
Can I use a VA loan more than once?
Yes. The VA home loan benefit can generally be used more than once. Depending on your situation, you may restore previously used entitlement or have remaining entitlement available while another VA loan is still outstanding. Your available entitlement and qualification should be reviewed for your specific scenario.
Can I have two VA loans at the same time?
It can be possible. Some eligible Veterans and service members can have more than one VA-backed loan at the same time when sufficient entitlement remains and the new loan meets applicable VA occupancy and lender qualification requirements.
Does a VA loan require a down payment?
VA-backed purchase loans can allow eligible borrowers to purchase with no down payment when the loan and borrower meet applicable VA and lender requirements. A down payment may still be required or strategically useful in certain situations.
What credit score do I need for a VA loan?
The Department of Veterans Affairs does not establish a single minimum credit score for all VA-backed loans. Lenders evaluate credit and may establish their own requirements, so qualification can vary by lender and by the overall loan profile.
What is VA loan entitlement?
VA loan entitlement is the amount of guaranty the Department of Veterans Affairs provides to an eligible borrower's VA-backed loan. Entitlement can affect how the benefit is used again, particularly when a borrower already has an outstanding VA loan or has not restored previously used entitlement.
Can VA disability income be used to qualify for a mortgage?
Eligible VA disability compensation can generally be considered as qualifying income when it is properly documented and meets applicable lending requirements. Certain non-taxable income may also receive special consideration when qualification is calculated.
What happens if I receive PCS orders after buying a home?
PCS orders do not automatically mean you must sell your home. Depending on your finances, entitlement, rental market, next duty station and long-term goals, selling, renting or keeping the property may each be worth evaluating.
Can I build a home with a VA loan?
VA-backed financing can be used for certain new-construction transactions when the borrower, property, builder and loan structure meet applicable requirements. VA construction lending is more specialized than a standard VA purchase, so the process and available loan structure should be reviewed before selecting a builder or property.
Latest Education
Latest From Veteran Community Mortgage
Clear answers, current VA guidance and practical homeownership
strategies for Veterans, service members and military families.
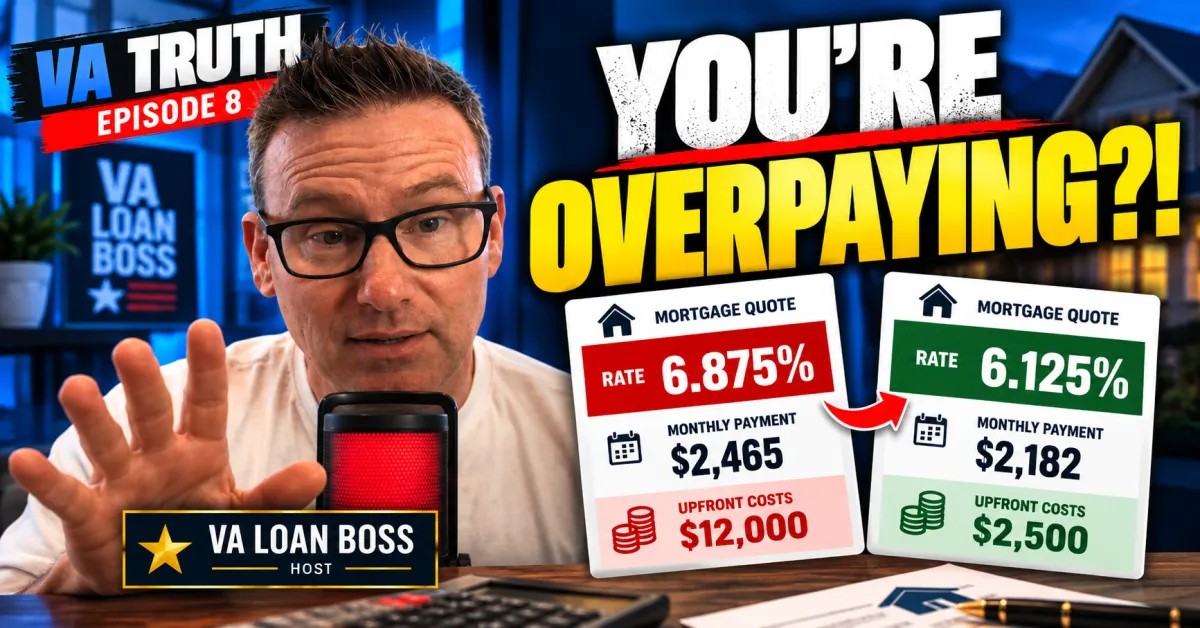
VA Loan Rates: Why the Lowest Mortgage Rate May Not Be the Best Deal
If you are a Veteran shopping for a VA mortgage, asking “What is your rate?” is not enough.
A mortgage rate only tells you part of the story. To understand whether you are getting a competitive VA loan, you also need to know what that rate costs.
A lender may quote a lower interest rate but charge discount points or higher lender fees to get there. Another lender may offer a slightly higher rate with little or no upfront cost. The lowest rate is not automatically the least expensive mortgage.
Does the VA Set Mortgage Rates?
No.
The Department of Veterans Affairs guarantees a portion of eligible VA home loans, but private lenders make the loans and determine their pricing.
That means VA mortgage rates, discount points, lender fees and lender credits can vary from one lender to another.
This is why Veterans should compare the complete mortgage offer instead of assuming every VA lender will offer the same deal.
What Are Discount Points on a VA Loan?
Discount points are upfront fees paid in exchange for a particular interest rate.
One point generally equals 1% of the loan amount.
For example, on a $500,000 mortgage:
1 point = $5,000
2 points = $10,000
If one lender offers a lower rate but charges two points, that lower rate could require $10,000 in additional upfront cost.
That does not automatically make the offer bad.
It also does not automatically make it good.
The real question is whether the monthly savings from the lower rate justify the additional upfront cost.
Ask This Question: “What Does That Rate Cost?”
This is one of the simplest ways Veterans can improve the mortgage-shopping conversation.
Instead of only asking:
“What is your VA mortgage rate?”
Ask:
“What does that rate cost?”
Then look at the complete structure of the loan.
Compare:
Interest rate
Discount points
Origination or lender charges
Lender credits
Loan amount
Monthly principal and interest
Estimated cash to close
Lock period
Other relevant loan costs
The goal is to compare similar loan structures instead of comparing one attractive number.
Why Comparing Monthly Payments Can Also Be Misleading
Veterans sometimes compare two mortgage quotes based only on the monthly payment.
That can create another problem.
A quoted payment can change based on the assumptions used for property taxes, homeowners insurance, loan amount, interest rate and other items.
If two lenders use different assumptions, one payment may look lower even though the underlying mortgage is not necessarily better.
Compare the same loan amount, on the same day, with similar assumptions and lock periods whenever possible.
Are VA Loan Rates Lower Than Conventional Mortgage Rates?
VA financing can offer very competitive mortgage pricing because eligible loans are backed by a VA guaranty.
However, that does not mean a VA loan will always be the best financial option in every scenario or that every lender will price a VA loan the same way.
An eligible Veteran comparing VA and conventional financing should look at the actual numbers for both options.
Do not assume conventional is better simply because you have excellent credit.
Do not assume VA is better simply because you are eligible.
Run the comparison.
How Should Veterans Compare VA Lenders?
Start with three simple steps.
1. Compare quotes from the same day
Mortgage markets move. A quote from Monday should not automatically be compared with a quote from Friday as if market conditions were identical.
2. Compare the rate and the cost of the rate
Ask whether discount points are included and how much they cost.
3. Compare the Loan Estimates
A Loan Estimate can help you compare the actual structure of competing mortgage offers, including loan costs, credits and estimated cash to close.
Do not make the decision from a screenshot, advertisement or text message containing only an interest rate.
The VA Loan Is a Benefit. The Mortgage Is Still a Financial Decision.
The VA home loan is one of the most powerful benefits available to eligible Veterans and military families.
But having access to the benefit does not mean every VA mortgage offer is automatically a good deal.
The lender matters.
The pricing matters.
The fees matter.
And understanding the numbers matters.
You do not need to become a mortgage expert.
You just need to know the right questions to ask.
The next time someone quotes you a VA mortgage rate, start with this one:
“What does that rate cost?”
Watch Episode 8 of VA Truth
Jason breaks this entire concept down in Episode 8 of VA Truth: “Veterans: Your VA Mortgage Rate Could Be Costing You Thousands.”
Watch the video, then use the questions above when comparing your next VA mortgage offer.
VA Truth is built to help Veterans and military families understand the benefits they earned, cut through the myths, and make better-informed homeownership decisions.
IMPORTANT: Mortgage rates and pricing change frequently. Examples in this article are educational only and are not current rate quotes, loan offers, or commitments to lend. Actual loan pricing depends on the borrower, property, lender, market conditions, lock period and loan structure.

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Have a VA Loan Question?
Start With the Strategy.
You do not need to figure out the VA home loan on your own. Whether you are
buying, refinancing, PCSing, retiring from the military or planning a new
construction home, start by understanding your options and the next step that
makes sense for your situation.