V
VA Home Loans for Veterans & Military Families
VA Home Loan Experts for Veterans & Military Families
Using your VA home loan benefit should not be confusing.
Veteran Community Mortgage helps Veterans, active-duty service
members and military families understand their VA home loan options,
build the right strategy and move forward with confidence from first-time
homebuying and PCS moves to refinancing, military retirement and VA construction.
⚑ VA Home Loan Education
♙20+ Years of Mortgage Experience
♡ Veteran & Military Family Focused
☆ Led by VA Loan Educator Jason Stier
VA Topics
Your VA Benefit Is More Than a Loan Program. Know How to Use It.
The VA home loan is one of the most valuable benefits earned through military service,
but the rules can feel complicated. Our job is to make them easier to understand and
help you build a strategy around your actual situation.
VA Loan Eligibility & Entitlement
Understand who is eligible, how entitlement works, whether you can use the benefit more than once and what happens when you already have a VA loan.
Buying With a VA Loan
Buying With a VA Loan
Learn how VA financing works from pre-approval through closing, including offers, closing costs, seller concessions and the VA appraisal.
PCS & Military Moves
Buying before a PCS? Deciding whether to sell or rent? Moving before the family arrives? Start with guidance built around the realities of military relocation.
Military Retirement &
VA Disability
Understand how military retirement, pending retirement and eligible VA disability income may affect your homebuying strategy and mortgage qualification.
VA Refinancing &
Assumptions
Learn how VA IRRRLs, VA cash-out refinancing and VA loan assumptions work and when each option may or may not make sense.
VA Construction Loans
Want to build instead of buy an existing home? Learn how VA construction and One-Time Close financing can work for eligible Veterans and service members.
Meet The VA Loan Boss
With over 21 years of experience in the mortgage industry, Jason Stier has built a reputation as a trusted, knowledgeable, and approachable loan officer who goes above and beyond for his clients. Known as the “VA Loan Boss,” Jason combines expertise with a deep passion for serving Veterans, military members, and their families through Veteran Community Mortgage. His mission? To ensure those who’ve served our country can navigate the path to homeownership with confidence and ease.
Jason’s years in the industry have sharpened his greatest skills: expert communication, problem-solving, and the ability to simplify complex financial processes. Whether breaking down the nuances of VA loan benefits or navigating challenging credit situations, Jason excels at turning what can feel overwhelming into an empowering experience.
When Jason isn't helping Veterans achieve their homeownership goals, he enjoys spending quality time with my family, traveling, and staying active through golf and pickleball. He's also passionate about connecting with and supporting Veteran-focused charities and organizations that make a positive impact in the lives of those who have served our country. Giving back to the Veteran community is something he values deeply, both professionally and personally.
Start With Your Situation
Where Are You in the Process?
You do not need to know every VA rule before you start. Find the situation that
looks most like yours and begin there.
I Want to Buy a Home
Understand your VA eligibility, buying power,
pre-approval and what to expect from offer to closing.
I Have PCS Orders
Build a housing strategy around your move,
timeline, current home and next duty station.
I Already Own a Home
Explore VA refinancing, assumptions, remaining entitlement and options for using your benefit again.
I Want to Build a Home
Learn how VA construction and One-Time Close
financing can help eligible borrowers finance a new build.
VA Home Loan Knowledge Center
Get Straight Answers
About the VA Home Loan
You should not have to dig through lender sales pages, social media
opinions and outdated information to understand your VA benefit.
The Veteran Community Mortgage Knowledge Center is being built to
answer the questions Veterans and military families actually ask in
plain English, with direct answers, real-world context and links to
authoritative sources when the rules matter.
The VA Process
How the VA Home Loan Process Works
Every situation is different, but most VA home purchases
move through these five stages.
Build Your Strategy
We start with your goals, military timeline, finances and how you plan to use the property.
VA Loan Pre-Approval
We review your qualification and VA eligibility so you understand your buying range before you start making offers.
Find the Right Home
You and your real estate agent search for a property that fits your needs, budget and VA financing strategy.
Appraisal & Underwriting
The property and loan are reviewed, including the VA appraisal and the documentation required for final loan approval.
Closing
Once the loan is cleared and closing requirements are satisfied, you sign the final documents and complete the purchase.
Why VCM
Why Veteran Community Mortgage?
We built Veteran Community Mortgage around a simple belief: military families
deserve more than a lender who happens to offer VA loans. They deserve
people who understand the benefit, teach the process and know the questions
to ask before problems show up.
VA-Focused Guidance
Our education, process and resources are
built around the VA home loan and the situations
military families regularly face.
Education Before Pressure
We want you to understand the benefit,
the numbers and the tradeoffs before you
make a decision.
Strategy for Real Military Life
PCS orders, deployments, retirement, disability income, existing VA loans and future moves can change the strategy. We account for the bigger picture.
I Want to Build a Home
Learn how VA construction and One-Time Close
financing can help eligible borrowers
finance a new build.
Don't take my word for it
Frequently Asked Questions
Can I use a VA loan more than once?
Yes. The VA home loan benefit can generally be used more than once. Depending on your situation, you may restore previously used entitlement or have remaining entitlement available while another VA loan is still outstanding. Your available entitlement and qualification should be reviewed for your specific scenario.
Can I have two VA loans at the same time?
It can be possible. Some eligible Veterans and service members can have more than one VA-backed loan at the same time when sufficient entitlement remains and the new loan meets applicable VA occupancy and lender qualification requirements.
Does a VA loan require a down payment?
VA-backed purchase loans can allow eligible borrowers to purchase with no down payment when the loan and borrower meet applicable VA and lender requirements. A down payment may still be required or strategically useful in certain situations.
What credit score do I need for a VA loan?
The Department of Veterans Affairs does not establish a single minimum credit score for all VA-backed loans. Lenders evaluate credit and may establish their own requirements, so qualification can vary by lender and by the overall loan profile.
What is VA loan entitlement?
VA loan entitlement is the amount of guaranty the Department of Veterans Affairs provides to an eligible borrower's VA-backed loan. Entitlement can affect how the benefit is used again, particularly when a borrower already has an outstanding VA loan or has not restored previously used entitlement.
Can VA disability income be used to qualify for a mortgage?
Eligible VA disability compensation can generally be considered as qualifying income when it is properly documented and meets applicable lending requirements. Certain non-taxable income may also receive special consideration when qualification is calculated.
What happens if I receive PCS orders after buying a home?
PCS orders do not automatically mean you must sell your home. Depending on your finances, entitlement, rental market, next duty station and long-term goals, selling, renting or keeping the property may each be worth evaluating.
Can I build a home with a VA loan?
VA-backed financing can be used for certain new-construction transactions when the borrower, property, builder and loan structure meet applicable requirements. VA construction lending is more specialized than a standard VA purchase, so the process and available loan structure should be reviewed before selecting a builder or property.
Latest Education
Latest From Veteran Community Mortgage
Clear answers, current VA guidance and practical homeownership
strategies for Veterans, service members and military families.
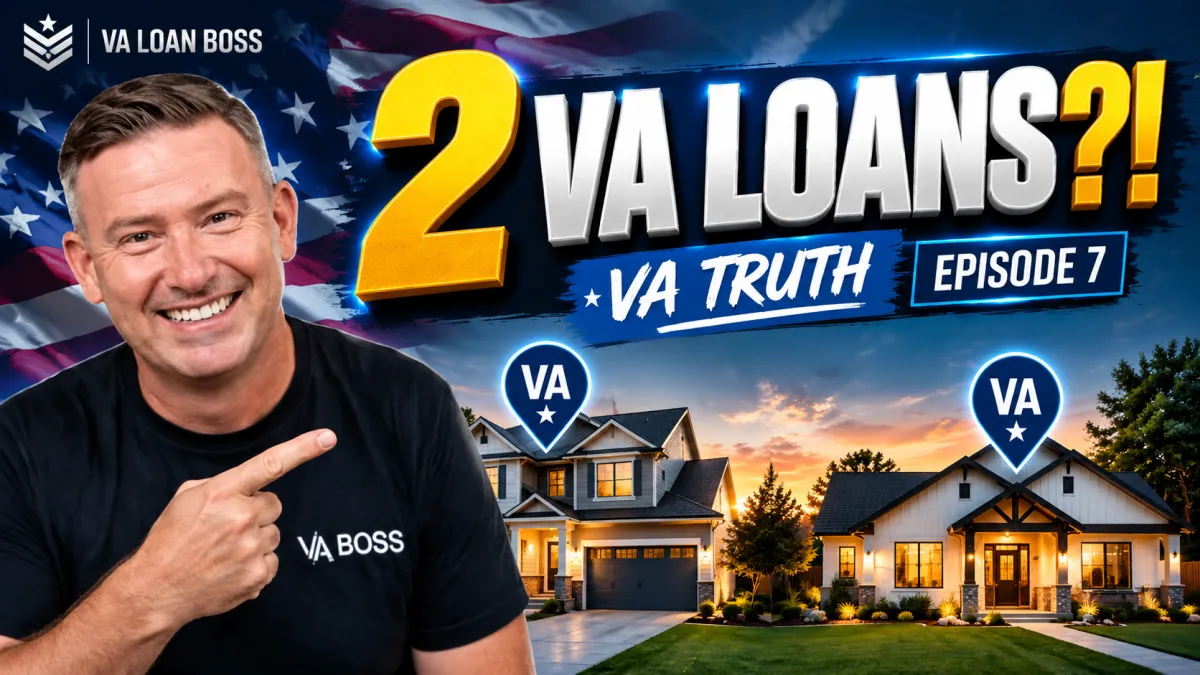
Can You Have Two VA Loans at the Same Time and Here Is What Veterans Actually Need to Know
The VA Loan Myth That Is Costing Veterans Real Money
The VA loan can only be used once. That belief is wrong and acting on it without understanding the full picture of how VA entitlement actually works can lead veterans to make major financial decisions that cost them significantly. Jason Stier addresses this directly in Episode 7 of VA Truth because the consequences of this misconception are too significant to leave unaddressed.
The Short Answer
Potentially yes. A veteran or eligible service member may be able to keep a home that already has a VA loan on it and use remaining VA entitlement toward the purchase of another primary residence. Having an existing VA loan does not automatically mean you have to sell the current property before using the benefit again.
What Remaining VA Entitlement Actually Means
VA entitlement is not a single-use benefit that disappears after the first loan closes. It is a guarantee amount that backs the lender's risk. When a veteran uses the VA benefit to purchase a home some entitlement is tied to that loan. But depending on the loan amount and the county conforming loan limits there may be entitlement remaining that can be applied to a second property.
That remaining entitlement is what makes a simultaneous second VA loan possible in qualifying situations. The amount available and whether a down payment is required on the new purchase depends on how much entitlement is already in use and what the conforming loan limits are in the county where the new property is located.
How PCS Orders Change the Calculation
A permanent change of station is one of the most common situations where the dual VA loan question becomes immediately relevant. A service member who owns a VA-financed home in one location and receives orders to relocate may not want to sell the current property. If the numbers on keeping it as a rental work and remaining entitlement supports a new purchase at the new duty station the veteran may have a path to both keeping the existing property and using VA financing on the new one.
The new property still needs to meet VA occupancy requirements which means the veteran must intend to occupy it as a primary residence. But the existing VA-financed property does not have to be sold to make that happen in the right circumstances.
When a Down Payment May Be Required
Zero down is one of the most powerful features of the VA loan benefit. But when entitlement is already in use on an existing loan the remaining entitlement available for a new purchase may not fully cover the new loan amount at zero down.
In that situation the veteran may need to bring a down payment to cover the gap between what the remaining entitlement supports and the actual purchase price. Understanding exactly how much entitlement is available and what it supports at zero down versus what requires a contribution is the calculation worth running before any decision is made.
How Entitlement Can Be Restored
When a VA-financed property is sold and the loan is paid off the entitlement that was tied to that loan can typically be restored. A veteran who has used the VA benefit once, sold the property, and paid off the loan can generally restore their full entitlement and use the benefit again as if it were the first time.
Restoration requires a formal request and the process has specific steps. But for veterans who believe they can only use the VA loan once in a lifetime this is important information that changes the picture significantly.
The Bigger Lesson
Do not make a major financial decision because someone told you the VA loan can only be used once. Understand your entitlement. Understand your options. Then make the decision that actually makes sense for your family's specific situation.
Running the numbers before automatically selling a property could reveal that keeping it as a rental while using remaining entitlement on a new purchase produces a better long-term financial outcome than starting fresh.
Subscribe to VA Loan Boss for VA Truth and reach out to Jason Stier with any questions about your specific entitlement situation.
Sources
VA.gov
MilitaryOneSource.mil
ConsumerFinancialProtectionBureau.gov
MortgageNewsDaily.com
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Have a VA Loan Question?
Start With the Strategy.
You do not need to figure out the VA home loan on your own. Whether you are
buying, refinancing, PCSing, retiring from the military or planning a new
construction home, start by understanding your options and the next step that
makes sense for your situation.