VA Loan Rates: Why the Lowest Mortgage Rate May Not Be the Best Deal
If you are a Veteran shopping for a VA mortgage, asking “What is your rate?” is not enough.
A mortgage rate only tells you part of the story. To understand whether you are getting a competitive VA loan, you also need to know what that rate costs.
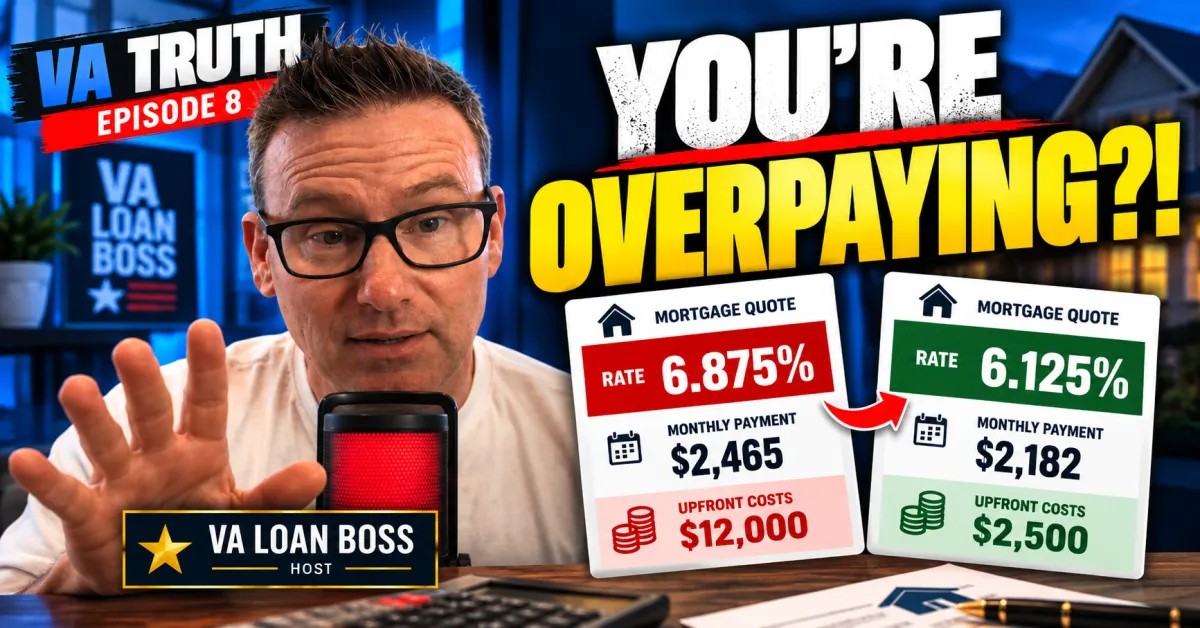
A lender may quote a lower interest rate but charge discount points or higher lender fees to get there. Another lender may offer a slightly higher rate with little or no upfront cost. The lowest rate is not automatically the least expensive mortgage.
Does the VA Set Mortgage Rates?
No.
The Department of Veterans Affairs guarantees a portion of eligible VA home loans, but private lenders make the loans and determine their pricing.
That means VA mortgage rates, discount points, lender fees and lender credits can vary from one lender to another.
This is why Veterans should compare the complete mortgage offer instead of assuming every VA lender will offer the same deal.
What Are Discount Points on a VA Loan?
Discount points are upfront fees paid in exchange for a particular interest rate.
One point generally equals 1% of the loan amount.
For example, on a $500,000 mortgage:
1 point = $5,000
2 points = $10,000
If one lender offers a lower rate but charges two points, that lower rate could require $10,000 in additional upfront cost.
That does not automatically make the offer bad.
It also does not automatically make it good.
The real question is whether the monthly savings from the lower rate justify the additional upfront cost.
Ask This Question: “What Does That Rate Cost?”
This is one of the simplest ways Veterans can improve the mortgage-shopping conversation.
Instead of only asking:
“What is your VA mortgage rate?”
Ask:
“What does that rate cost?”
Then look at the complete structure of the loan.
Compare:
Interest rate
Discount points
Origination or lender charges
Lender credits
Loan amount
Monthly principal and interest
Estimated cash to close
Lock period
Other relevant loan costs
The goal is to compare similar loan structures instead of comparing one attractive number.
Why Comparing Monthly Payments Can Also Be Misleading
Veterans sometimes compare two mortgage quotes based only on the monthly payment.
That can create another problem.
A quoted payment can change based on the assumptions used for property taxes, homeowners insurance, loan amount, interest rate and other items.
If two lenders use different assumptions, one payment may look lower even though the underlying mortgage is not necessarily better.
Compare the same loan amount, on the same day, with similar assumptions and lock periods whenever possible.
Are VA Loan Rates Lower Than Conventional Mortgage Rates?
VA financing can offer very competitive mortgage pricing because eligible loans are backed by a VA guaranty.
However, that does not mean a VA loan will always be the best financial option in every scenario or that every lender will price a VA loan the same way.
An eligible Veteran comparing VA and conventional financing should look at the actual numbers for both options.
Do not assume conventional is better simply because you have excellent credit.
Do not assume VA is better simply because you are eligible.
Run the comparison.
How Should Veterans Compare VA Lenders?
Start with three simple steps.
1. Compare quotes from the same day
Mortgage markets move. A quote from Monday should not automatically be compared with a quote from Friday as if market conditions were identical.
2. Compare the rate and the cost of the rate
Ask whether discount points are included and how much they cost.
3. Compare the Loan Estimates
A Loan Estimate can help you compare the actual structure of competing mortgage offers, including loan costs, credits and estimated cash to close.
Do not make the decision from a screenshot, advertisement or text message containing only an interest rate.
The VA Loan Is a Benefit. The Mortgage Is Still a Financial Decision.
The VA home loan is one of the most powerful benefits available to eligible Veterans and military families.
But having access to the benefit does not mean every VA mortgage offer is automatically a good deal.
The lender matters.
The pricing matters.
The fees matter.
And understanding the numbers matters.
You do not need to become a mortgage expert.
You just need to know the right questions to ask.
The next time someone quotes you a VA mortgage rate, start with this one:
“What does that rate cost?”
Watch Episode 8 of VA Truth
Jason breaks this entire concept down in Episode 8 of VA Truth: “Veterans: Your VA Mortgage Rate Could Be Costing You Thousands.”
Watch the video, then use the questions above when comparing your next VA mortgage offer.
VA Truth is built to help Veterans and military families understand the benefits they earned, cut through the myths, and make better-informed homeownership decisions.
IMPORTANT: Mortgage rates and pricing change frequently. Examples in this article are educational only and are not current rate quotes, loan offers, or commitments to lend. Actual loan pricing depends on the borrower, property, lender, market conditions, lock period and loan structure.
